
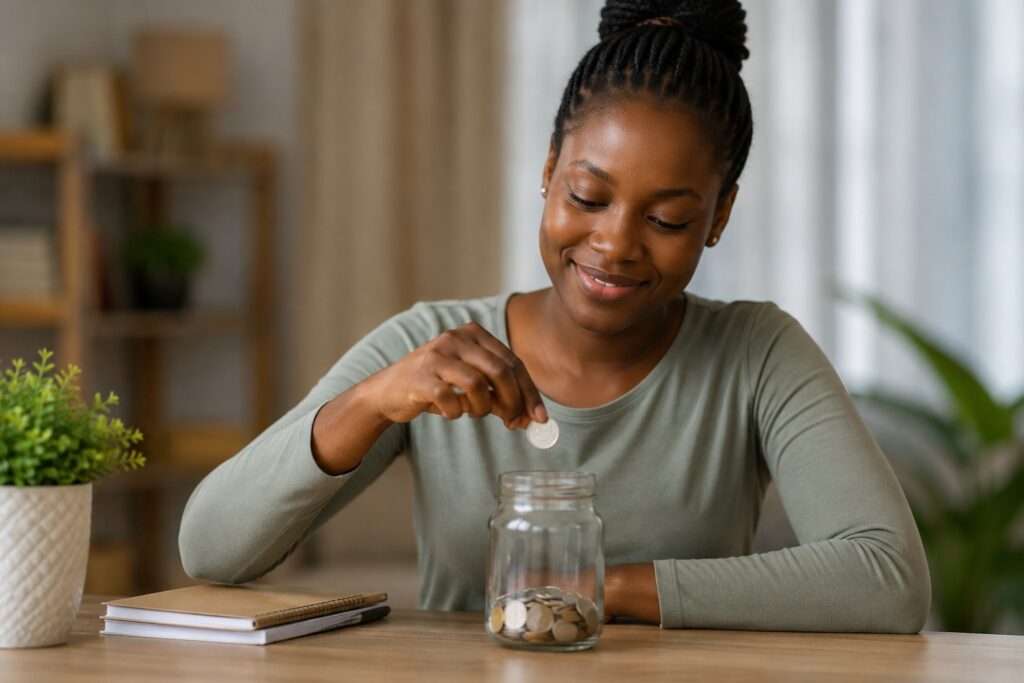
You do not need to earn a lot of money to build your savings. Developing a saving habit starts with making small financial decisions and sticking to them over time.
That is the message behind five practical tips shared during Saving Week 2026, which aims to encourage Rwandans to take greater control of their finances and plan for the future.
The recommendations include setting aside money as soon as you receive your income, keeping savings separate from everyday spending, starting with small amounts, investing wisely and joining savings groups.
The 2024 FinScope survey shows that 85% of adults in Rwanda save money through different channels. While this reflects growing awareness of the importance of saving, many people still struggle to put money aside after covering their daily expenses.
Here are five practical ways to build a saving habit, regardless of your income.
1. Make saving your first priority
One of the easiest ways to save consistently is to put some money aside as soon as you receive your salary or other income.
Rather than paying all your expenses first and saving whatever remains, decide in advance how much you can afford to save. Set that amount aside before spending the rest.
This approach helps you make saving a regular part of your financial routine instead of treating it as something you do only when you have extra money.
2. Keep your savings away from everyday spending
It is easier to protect your savings when they are not mixed with the money you use for daily expenses.
Consider opening a separate bank account, using a SACCO or choosing another reliable saving option. This allows you to monitor your progress and reduces the temptation to spend money you had intended to keep.
3. Start with what you have
You do not need a large salary to become a saver. The important thing is to start with an amount you can manage and contribute regularly.
For instance, putting aside RWF 500 every day would give you RWF 15,000 after 30 days and RWF 180,000 over a year, excluding any interest earned.
Small contributions may seem insignificant at first, but they can grow into a meaningful financial reserve when maintained consistently.
4. Put your money to work through investment
While saving helps you prepare for future expenses, investing offers an opportunity to grow your money by putting it into income-generating activities or assets.
Depending on your financial capacity and interests, you could consider starting or expanding a business, buying shares or exploring other legitimate investment opportunities.
However, every investment carries some level of risk. Before committing your money, understand how the opportunity works, the returns you could earn and the possibility of losing part or all of your investment. It is also important to keep enough money for your essential needs rather than investing everything you have.
5. Build savings together through a group
Joining a savings group, such as an Ikimina, tontine or Village Savings and Loan Association (VSLA), can make it easier to save regularly.
Members contribute agreed amounts at set intervals and decide collectively how the funds will be managed or used. The arrangement allows people to pool resources, support one another and work towards shared financial goals.
For such groups to succeed, members need clear rules, transparent records and proper financial management to avoid disagreements and build trust.
Saving is a habit, not a measure of wealth
Having savings can make a significant difference when unexpected expenses arise. It can also help individuals finance education, build homes, expand businesses and pursue other long-term goals without relying entirely on borrowing.
The government has also identified domestic savings and investment as important drivers of economic growth. During Saving Week 2025, the Ministry of Finance and Economic Planning announced a target of raising domestic savings to 25.9% of Rwanda’s gross domestic product (GDP) by 2029.
Higher domestic savings can provide more resources for investment in productive sectors, supporting economic activity and national development.
As Saving Week 2026 highlights, building financial security does not have to begin with a high salary. It starts with using what you have wisely, setting realistic goals and making saving a consistent habit.